Welcome to the latest edition of the Greater Seattle Housing Market Review. As always, to jump straight to the stats, you can do so by clicking here for the SFR update and here for the condo update. For more information, continue reading below!
I'm sure I'm not alone when I can admit that, regardless of who you voted for, whether your candidate, party, initiative, etc won or lost, we can all be extremely grateful that the midterms are over. No longer will we be bombarded with calls, texts, emails, postcards, etc. We're free!
What do the midterms have to do with housing? Well, nothing really. At least not directly. Remember, financial markets hate volatility and instability. The weeks and months leading into the midterms, it was unknown what political direction the country was going to lean, and therefore projecting financial policy was simply speculative. During times of uncertainty, markets get conservative and price accordingly. We saw this first hand with mortgage rates.
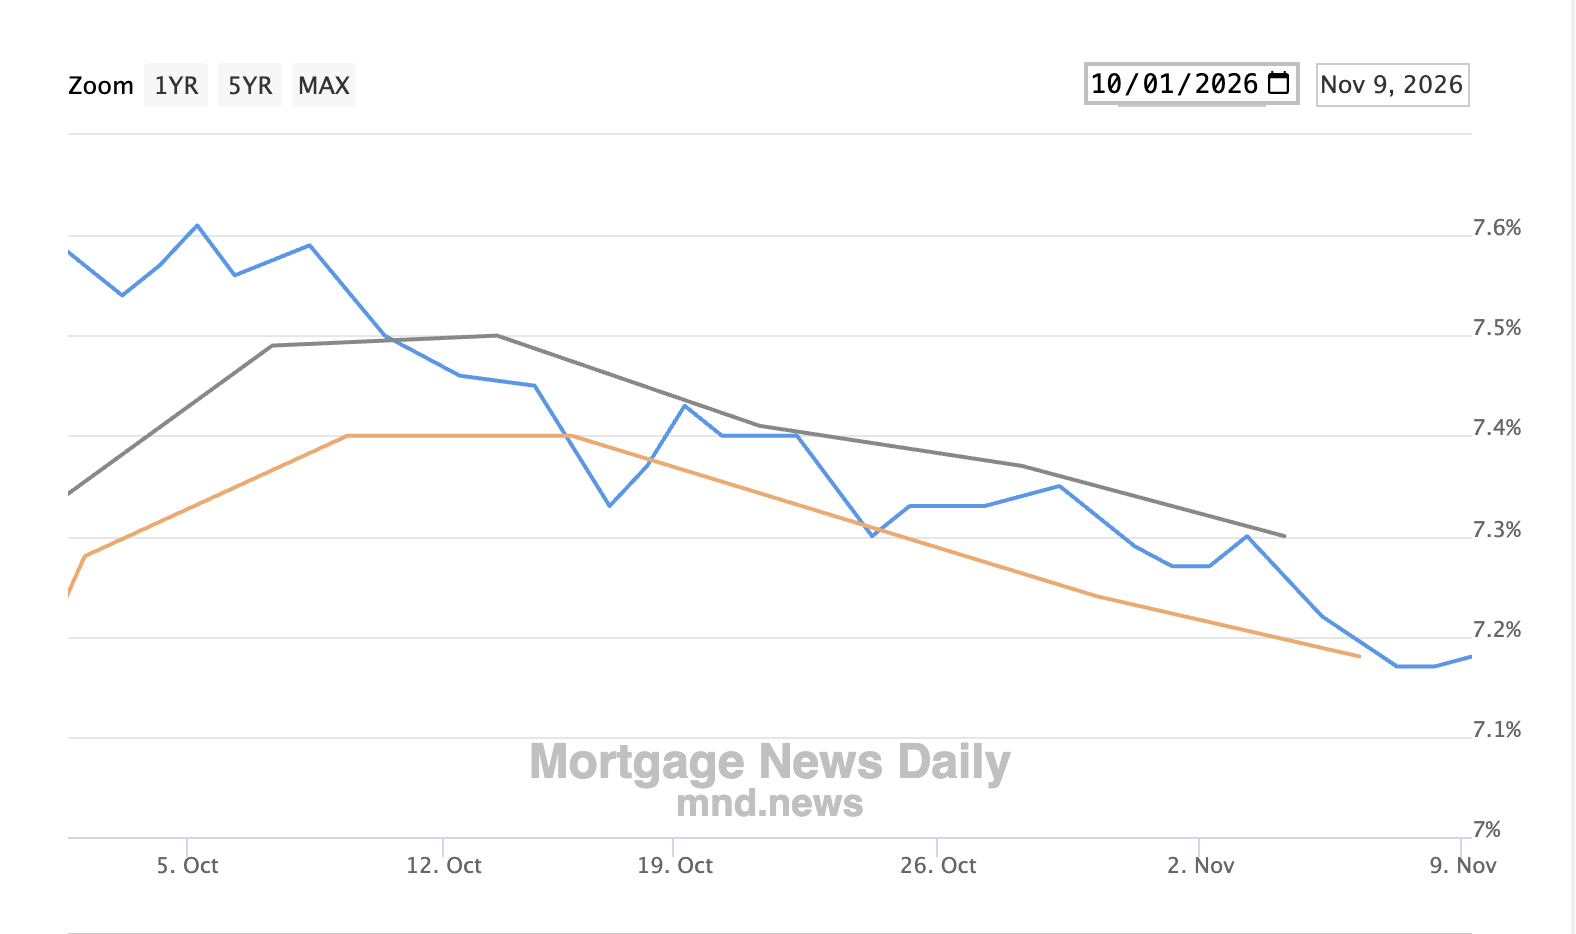
At the time I'm creating this article, mortgage rates are a solid .25% lower from where they started in October. I know that doesn't sound like a lot, and I'm not throwing parades over it, but it's trending in the right direction. However, given the decline in the 10-year treasury, you would think rates would be lower. See below:
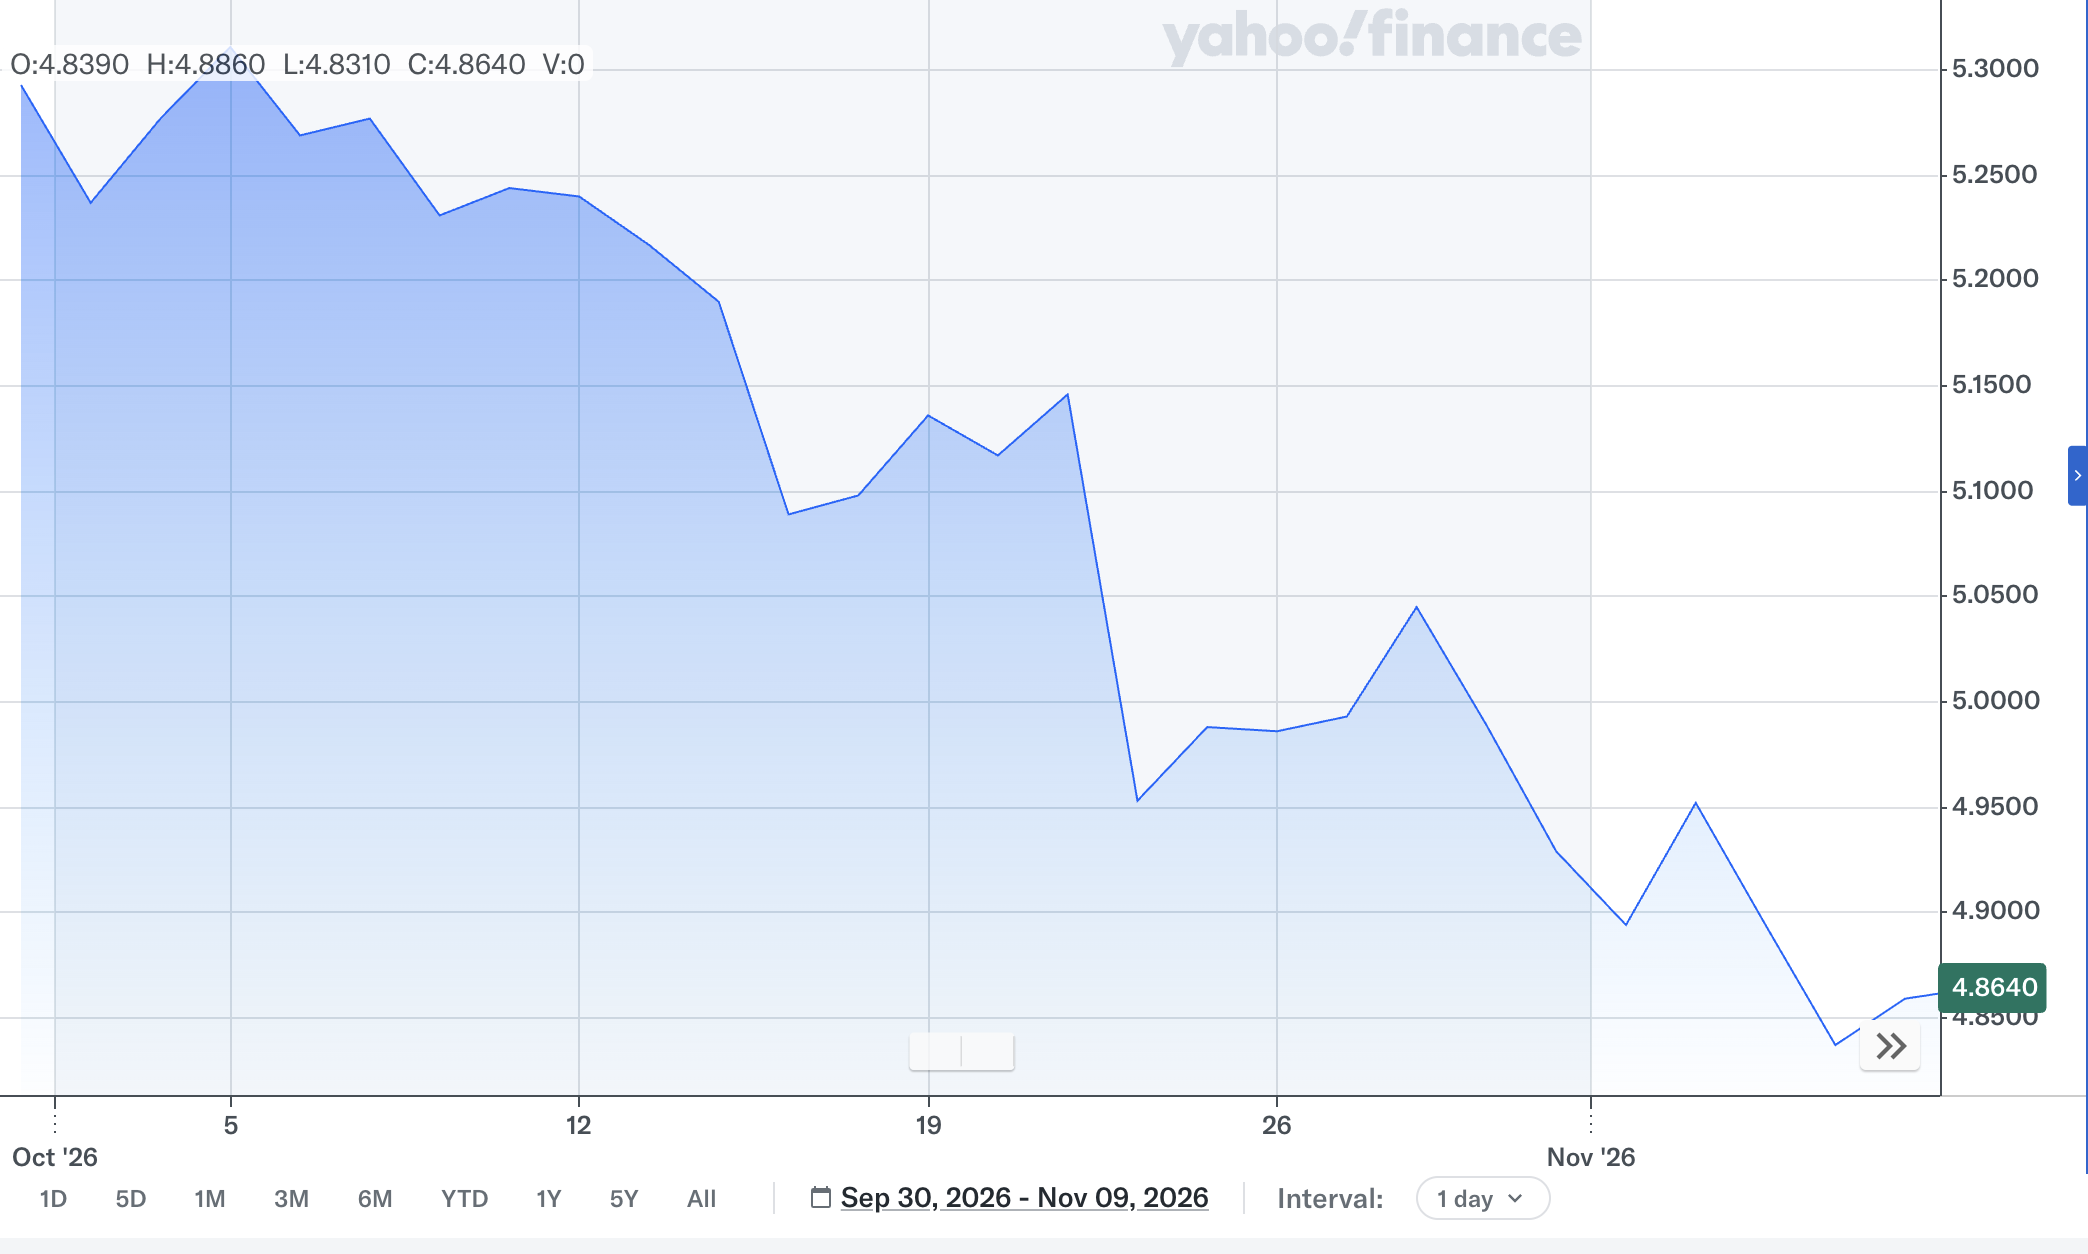
Over that same period interest rates dropped about .25% the 10 year t-bond dropped almost .50 bps. All things remaining equal, rates should have dropped roughly another .25% and should be even lower than they are. What gives?
Don't forget about my update a few months back. Mortgage spreads were pretty consistently trending about 2 points above the 10-year note. Again, today at that spread we'd be back under 7% to rates, yet we're not. Why? Too much volatility. When markets are uber volatile, traders will trade on the side of caution. That means being more willing to price disproportionately high when rates are trending north, and slow to improve their price when rates trend lower. That's why the spreads right now are looser/larger than they've been recently (and still higher than historical averages).
And that's where buyers can (hopefully) feel encouraged. Rates are slowly coming down and even if geopolitical events remain unresolved (the Iran conflict) rates can still improve simply by the spreads tightening, even as we approach next months FED meeting where it's widely expected they'll raise their rate. Add in geopolitical stability, which creates lower oil/energy prices diminishing fears of increasing inflation, and there's a chance we could experience strong downward pressure on interest rates. Don't get me wrong, that's a HUGE if all that comes together. Kind of like hitting a 4 leg parlay for all you degenerate sports gamblers out there. But, it can happen and if/when it does, we'll see buyers return with a surgeance.
Real estate professionals are certainly hoping that happens. Did you know that mortgage applications recently hit their lowest levels in over 30 years?!? Check out this article. Thanks to a quick Google search, we've gained nearly 77 million people since the summer of 1995, yet we're at similar levels of mortgage applications. Granted, not every new resident is a future home buyer, nor does that include cash buyers since they don't apply for mortgages, but that is a powerful stat. 77 million more people yet the same level of mortgage applications. Wow. Don't forget, we are in year 4 of a real estate recession. It's simply a recession on overall sales numbers. Prices and rates both remain elevated. I expect another year of the same for 2027.
Onto the stats, starting with the single family market:
Seattle - The October 2026 median sale price registered $982,500. That is down 6.4% YoY, yet up from $960,000 MoM. Inventory was up 22.4% YoY, yet the months of inventory dropped significantly from 4.15 months to 3.28 months.
Eastside - The median sale price registered $1,350,000. That is down 12.9% YoY and down from $1.425,000 MoM. This is the lowest median sale price for a home on the Eastside since February of 2023. Inventory is up 48.1% YoY and the months of inventory remains roughly unchanged at 4.32 months.
King County - The median sales price registered $925,000. That is down 7.2% YoY and down from $950,000 MoM. Inventory is up 37.9% YoY and the months of inventory dropped to 3.7 months from 4.1 MoM.
Perhaps most important throughout all this was the fact the absorption rate registered it's lowest reading of all time (since 2019 when I began tracking this) besting August by a hair, which was the previous low point.
Seattle Condo Stats - The median sale price in October 2026 for a Seattle condo registered $515,825. That is down 10.7% YoY and down from $530,000 MoM. Inventory is up 15% YoY and the months of inventory continues to swell at 8.34 months, which is thankfully unchanged MoM.
On a things can always be worse note, we stopped the trend of hitting a new all-time low for the absorption metric. Previous to October, we had 5 consecutive months where this number got worse than the month before, a previous all-time low. October was just a tad better, by .002 from the previous month, so things remain really difficult for Seattle condo sellers.
Have an amazing Thanksgiving! Onward!